Cyprus tax compliance does not revolve around one annual deadline. Companies and individuals can have monthly, quarterly and annual obligations running in parallel: PAYE, Social Insurance, GHS, VIES, VAT, OSS, provisional tax, personal income tax and corporate income tax all follow different timetables.
This 2027 calendar brings the main recurring dates together in one practical reference. It reflects the statutory framework and general deadlines in force as at October 2026. Cyprus authorities can grant extensions or move operational deadlines, and a date falling on a weekend or public holiday can also be handled differently depending on the specific tax or contribution. The page should therefore be updated during 2027 when official notices are issued.
For the tax rules behind the dates, see our main Tax in Cyprus guide.

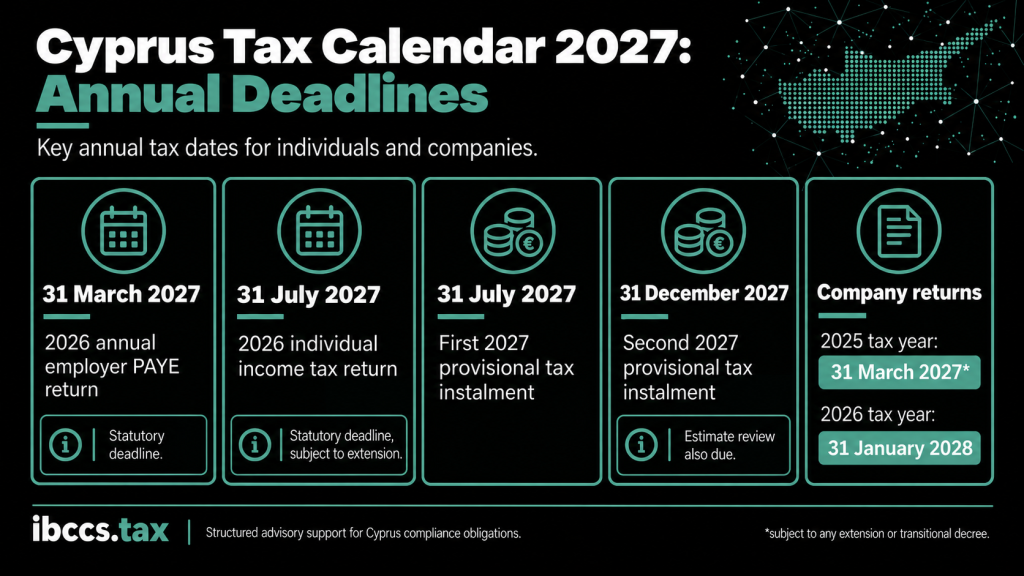
- 31 March 2027 is the statutory deadline for the 2026 annual employer PAYE and contribution withholding return.
- 31 July 2027 is the statutory deadline for the 2026 individual income tax return, subject to any extension issued by the Council of Ministers.
- 31 July 2027 is also the first provisional tax instalment deadline for the 2027 tax year for taxpayers within the provisional tax framework.
- 31 December 2027 is the second provisional tax instalment deadline and the final date for revising the 2027 provisional tax estimate under the ordinary timetable.
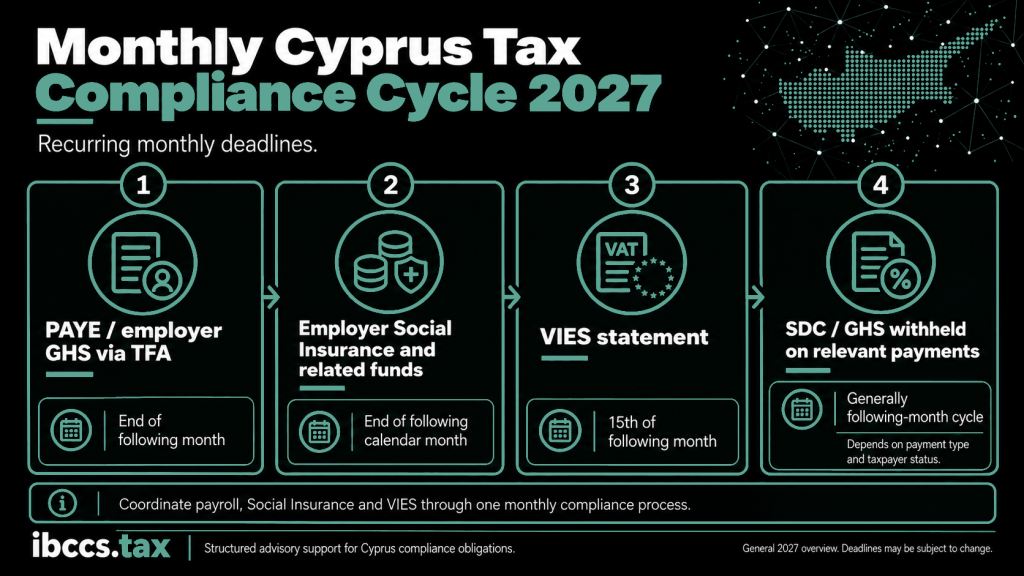
- Employer PAYE and GHS declarations are generally due by the end of the month following the payroll month.
- Employer Social Insurance contributions are generally payable by the end of the calendar month following the contribution month.
- VIES statements are generally due by the 15th day of the month following the reporting month.
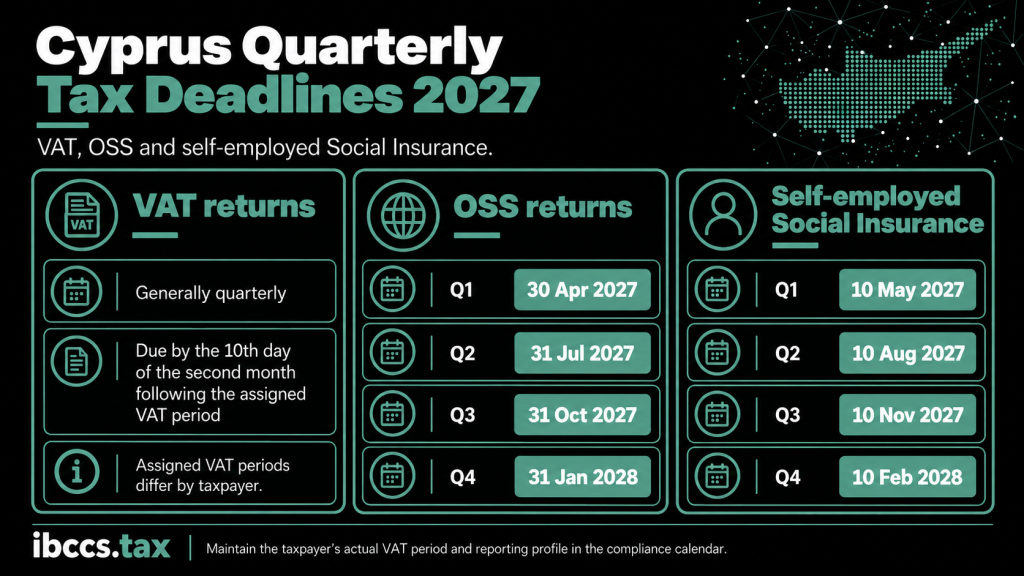
- VAT returns are generally quarterly and due by the 10th day of the second month following the end of the assigned VAT period; the exact return periods differ by taxpayer.
- OSS Union and Non-Union returns are generally quarterly and due by the end of the month following the relevant quarter.
- Company income tax deadlines depend on the tax year: the 2025 company return remains under the pre-2026 31 March timetable, while returns for tax years from 2026 move to 31 January of the second year following the tax year.
2027 Key Deadlines at a Glance
| Date / timing | Obligation | Who should review it |
| Monthly – end of following month | PAYE / employer GHS declaration and payment | Employers within the TFA monthly filing obligation |
| Monthly – end of following month | Employer Social Insurance and related funds | Employers |
| Monthly – 15th of following month | VIES statement | VAT-registered businesses with reportable intra-EU supplies |
| 31 March 2027 | 2026 annual employer PAYE return | Employers within the annual filing obligation |
| 31 July 2027 | 2026 individual income tax return – statutory deadline | Individuals required to file, subject to any extension |
| 31 July 2027 | First 2027 provisional tax instalment | Companies / self-employed taxpayers within provisional tax |
| 31 December 2027 | Second 2027 provisional tax instalment and estimate review | Companies / self-employed taxpayers within provisional tax |
| Periodic | VAT return and payment | VAT-registered persons according to assigned VAT period |
| Quarterly | OSS return and payment | Businesses using Union / Non-Union OSS |
| Quarterly + 40 days | Self-employed Social Insurance | Self-employed persons |
Important
A “tax calendar” should be treated as a control tool, not as a substitute for checking the taxpayer’s actual filing profile. VAT periods, cross-border reporting, payroll status and individual filing requirements differ between taxpayers.
January 2027
January is primarily a year-opening and prior-year close month. Employers should finalise December 2026 payroll, prepare the December PAYE / GHS declaration for filing by the end of January 2027 and arrange Social Insurance contributions for December 2026 by the applicable end-of-following-month deadline. VIES for December 2026 is generally due by 15 January 2027.
Businesses should also begin the annual payroll reconciliation for the 2026 employer return due on 31 March 2027, including Certificates of Emoluments and the reconciliation of payroll, TFA and Social Insurance records.
February 2027
January payroll liabilities generally fall due during February under the end-of-following-month cycle. Self-employed Social Insurance for Q4 2026 is ordinarily due by 10 February 2027. VIES for January 2027 is generally due by 15 February.
March 2027
The key annual employer date is 31 March 2027: the 2026 annual employer Income Tax and Contribution Withholding (PAYE) return is due under the statutory timetable introduced for tax years from 2026. Monthly February payroll liabilities also need to be handled under the ordinary cycle.
Under the pre-2026 corporate filing timetable, the statutory deadline for the 2025 company income tax return is also 31 March 2027 unless a later extension or transitional decree is issued. Because Cyprus has granted filing extensions in prior years, companies should monitor official Tax Department announcements rather than relying solely on the statutory date.
April 2027
March PAYE, employer GHS and Social Insurance fall into the ordinary following-month cycle. Businesses using OSS should also prepare the Q1 2027 OSS return, generally due by the end of April. VAT deadlines depend on the taxpayer’s assigned VAT period rather than the calendar quarter alone.
May 2027
Self-employed Social Insurance for Q1 2027 is ordinarily due by 10 May. April VIES is due by 15 May under the general rule, while April payroll liabilities are settled by the applicable end-of-May deadlines.
June 2027
June is an important review month for individuals with passive income. SDC self-assessment can apply on a six-monthly basis, including a 30 June payment date where tax has not been withheld at source. Separate GHS self-assessment or withholding obligations may apply depending on the income type and payer.
For dividend treatment, see Tax on dividends in Cyprus.
July 2027
July contains two of the most important annual Cyprus tax deadlines. The statutory deadline for the 2026 individual income tax return is 31 July 2027, although the Council of Ministers may extend the date by decree. Individuals should therefore prepare on the statutory timetable and treat any extension as additional time rather than the planned filing date.
The first provisional tax instalment for the 2027 tax year is also due by 31 July 2027 for companies and self-employed taxpayers within the provisional tax regime. The estimate should be based on expected full-year taxable income, not merely year-to-date cash receipts.
See Cyprus provisional tax for the estimation method and 75% rule.
August 2027
Self-employed Social Insurance for Q2 2027 is ordinarily due by 10 August. Employers continue the monthly PAYE / GHS and Social Insurance cycle for July payroll, while VIES for July is generally due by 15 August.
September 2027
September is a useful checkpoint for year-end tax forecasting. Companies should review actual taxable profit against the July provisional-tax estimate, identify material year-end transactions and schedule any transfer pricing, tax-loss, NID or IP Box analysis required before the second provisional tax instalment.
October 2027
Q3 OSS returns are generally due by the end of October. Businesses should also begin year-end payroll and corporate tax planning, particularly where bonuses, dividends, shareholder remuneration or significant cross-border payments are expected before 31 December.
November 2027
Self-employed Social Insurance for Q3 2027 is ordinarily due by 10 November. Companies should by this point have a substantially updated 2027 provisional tax forecast so that any revision can be made before the end-of-year deadline.
December 2027
The second provisional tax instalment for 2027 is due by 31 December 2027. The taxpayer should review the full-year estimate before payment. Where provisional taxable income is less than 75% of final taxable income, an additional 10% tax can apply to the relevant shortfall.
December is also the year-end point for payroll, dividend and other withholding reviews. Businesses should ensure that liabilities relating to December are captured for January 2028 reporting and that records are complete for annual employer, company and personal filings.
Recurring Monthly Deadlines in 2027
| Obligation | General deadline | Notes |
| PAYE / employee and employer GHS through TFA | End of following month | Applies to employers within monthly declaration obligation |
| Employer Social Insurance and related Social Insurance funds | End of following calendar month | Weekend / public holiday rule can move operational due date |
| VIES statement | 15th day of following month | For reportable intra-EU goods / services |
| SDC / GHS withheld on relevant payments | Generally following-month cycle | Exact liability depends on payment type and taxpayer status |
Employers should coordinate these dates through one payroll control process. See Payroll in Cyprus and Social Insurance in Cyprus.
Quarterly and Periodic Deadlines
VAT returns
Cyprus VAT returns are generally filed quarterly, but taxpayers are assigned different three-month periods. The return and VAT payable are generally due by the 10th day of the second month following the end of the VAT period. Businesses should therefore maintain their own VAT-period calendar rather than assuming every VAT return is due on the same dates.
See VAT in Cyprus for the full filing framework.
OSS
Union and Non-Union OSS returns are generally quarterly and due by the end of the month following the relevant quarter: Q1 by 30 April, Q2 by 31 July, Q3 by 31 October and Q4 by 31 January of the following year, subject to the OSS rules.
OSS filing and payment deadlines generally do not move to the next working day when they fall on a weekend or public holiday.
Self-employed Social Insurance
| Quarter | Standard payment date |
| Q1 2027 | 10 May 2027 |
| Q2 2027 | 10 August 2027 |
| Q3 2027 | 10 November 2027 |
| Q4 2027 | 10 February 2028 |
Company Tax Filing: 2025, 2026 and 2027 Tax Years
Cyprus changed the corporate income tax return timetable from the 2026 tax year. Up to tax year 2025, the statutory deadline is 31 March of the second year following the tax year. From tax year 2026 onwards, the deadline moves to 31 January of the second year following the tax year.
| Tax year | Statutory company return deadline |
| 2025 | 31 March 2027, subject to any extension / transitional decree |
| 2026 | 31 January 2028 |
| 2027 | 31 January 2029 |
For the filing framework and final balancing payment, see Cyprus corporate tax.
Individual Tax Return Deadline in 2027
The statutory deadline for the 2026 individual income tax return is 31 July 2027. The 2026 reform broadened the filing obligation and moved 2026 returns to Tax For All. The Council of Ministers retains the power to extend the filing date by decree, and recent years have seen extensions, so the live page should be updated if a 2027 extension is announced.
For rates and filing scope, see Cyprus personal income tax.
How to Use This Calendar in Practice
- Create separate recurring tasks for payroll, Social Insurance and VIES rather than one generic “monthly tax” reminder.
- Maintain the company’s actual assigned VAT period in the compliance calendar.
- Schedule provisional tax forecasts at least two to four weeks before 31 July and 31 December.
- Start annual employer reconciliation before March, not on the filing date.
- Prepare individual tax return information well before 31 July even if an extension is expected.
- Track dividends and passive income separately where SDC / GHS self-assessment can arise.
- Monitor Tax Department and Social Insurance announcements for extensions, system migrations and 2027-specific updates.
How IBCCS TAX Can Help With 2027 Compliance
IBCCS TAX supports businesses and individuals with recurring Cyprus tax and compliance obligations, including accounting, corporate and personal tax returns, provisional tax, VAT, VIES, OSS, payroll, Social Insurance and SDC / GHS declarations. A central compliance calendar can be built around the taxpayer’s actual registrations rather than a generic list of dates.
Our accounting services in Cyprus can be combined with payroll preparation and Social Insurance services for an integrated 2027 compliance workflow.
Frequently Asked Questions – Cyprus Tax Calendar 2027
1. What is the Cyprus individual tax return deadline in 2027?
The statutory deadline for the 2026 individual tax return is 31 July 2027, subject to any extension granted by decree.
2. When is provisional tax due in Cyprus in 2027?
The standard instalment dates are 31 July 2027 and 31 December 2027 for taxpayers within the provisional-tax framework.
3. When is the 2026 annual employer PAYE return due?
The statutory deadline is 31 March 2027.
4. When are Cyprus Social Insurance contributions due?
Employer contributions are generally due by the end of the calendar month following the contribution month.
5. When is VIES due in Cyprus?
VIES is generally due by the 15th day of the month following the month to which the statement relates.
6. When are VAT returns due in Cyprus?
VAT returns are generally quarterly and due by the 10th day of the second month after the end of the assigned VAT period. The exact periods differ by taxpayer.
7. When is the 2026 corporate income tax return due?
The 2026 company tax return is due by 31 January 2028 under the post-reform filing timetable.
8. Can Cyprus tax deadlines be extended?
Yes. The Tax Department and Council of Ministers can issue extensions or transitional arrangements. The statutory date should be used for planning and the live calendar updated when an official extension is announced.
Cyprus Non-Dom After 17 Years: Deemed Domicile and the Alternative SDC Method
Cyprus Non-Dom is often described as a 17-year tax benefit,
Read More
Cyprus Non-Dom Eligibility: Domicile of Origin, Domicile of Choice and the 17/20 Rule
Cyprus Non-Dom eligibility is often described too simply. A person
Read More
IBCCS TAX to Attend Plan ₿ Forum 2026 in Lugano, Switzerland
IBCCS TAX will be attending Plan ₿ Forum 2026 in
Read MoreImportant Note: This article provides general information on Cyprus tax and compliance rules. The correct treatment depends on the taxpayer, the nature and source of the income or transaction, tax residency and domicile, available exemptions, applicable double tax treaties and the facts of the case. It should not be treated as a substitute for transaction-specific tax or legal advice.