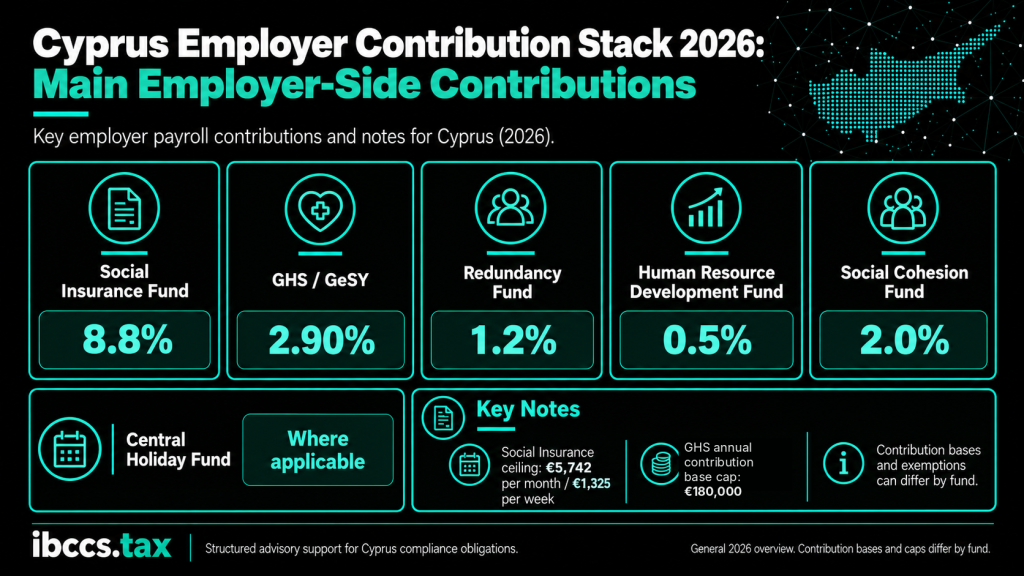
Social Insurance is a core part of employing people or working on a self-employed basis in Cyprus. For employers, the obligation is wider than a single 8.8% contribution: payroll can also involve GHS, the Redundancy Fund, Human Resource Development Fund, Social Cohesion Fund and, where applicable, the Central Holiday Fund.
The correct calculation depends on the employee’s insurable earnings, the annual maximum insurable earnings limits and whether a particular contribution is capped. Employers also need to register correctly, report payroll and pay contributions on time. Self-employed persons operate under a different contribution framework and payment timetable.
For the wider tax context, see our Tax in Cyprus guide. For the complete payroll workflow, see Payroll in Cyprus.

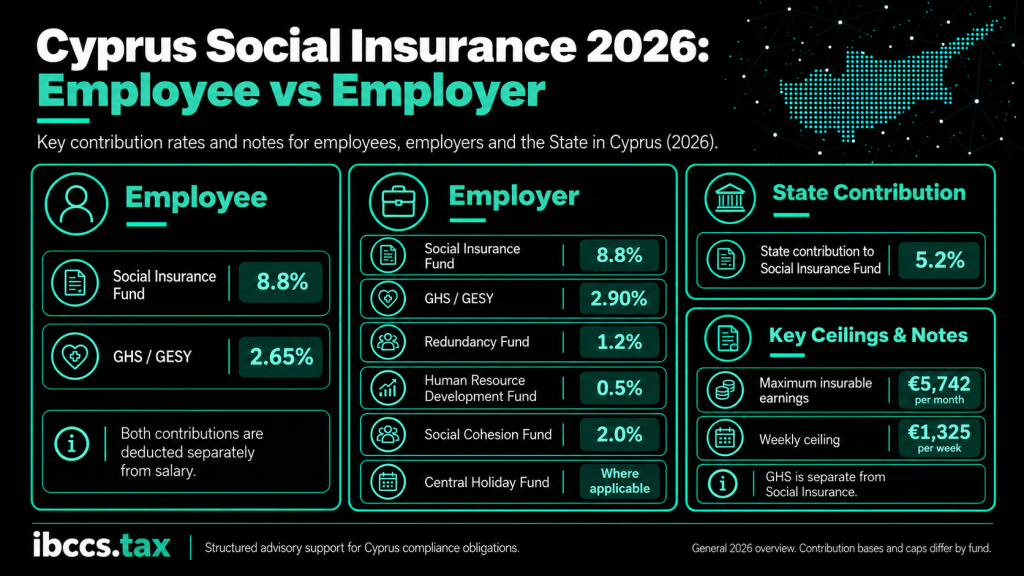
- For employees in 2026, Social Insurance Fund contributions are 8.8% for the employee and 8.8% for the employer, with the state contributing a further 5.2%.
- The maximum insurable earnings for monthly paid employees are €5,742 per month from 1 January 2026; for weekly paid employees the ceiling is €1,325 per week from 5 January 2026.
- The maximum insurable earnings ceiling applies to specified Social Insurance-related funds. It does not mean that every employer contribution stops at the same ceiling.
- GHS is separate: employees generally contribute 2.65% and employers 2.90% on remuneration under the GHS rules.
- Employers also pay 1.2% to the Redundancy Fund, 0.5% to the Human Resource Development Fund and 2% to the Social Cohesion Fund, subject to the applicable contribution base and rules.
- Central Holiday Fund contributions can also apply unless the employer is exempt and provides annual leave directly in accordance with the applicable requirements.
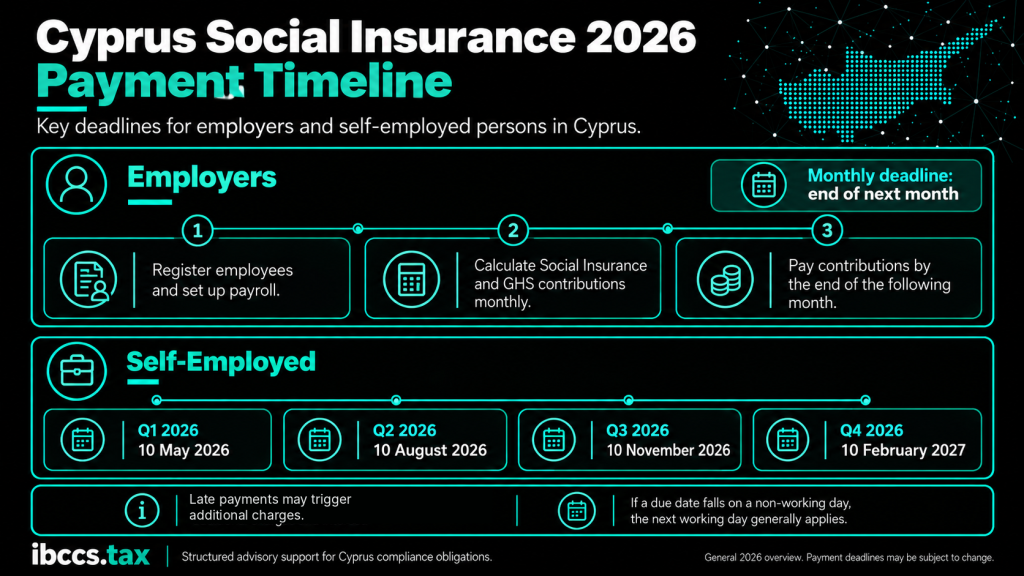
- Employer contributions are generally payable by the end of the calendar month following the month to which they relate.
- Self-employed persons generally pay 16.6% of the applicable insurable income, with the state contributing 5.2%; contributions are normally paid quarterly within 40 days after the end of the quarter.
- Social Insurance is not the same as PAYE or GHS. All three can appear in the payroll process and follow different legal rules.
Cyprus Social Insurance Rates in 2026
| Contribution | Employee | Employer | State / note |
| Social Insurance Fund | 8.8% | 8.8% | State contributes 5.2% |
| GHS / GESY | 2.65% | 2.90% | Separate healthcare contribution framework |
| Redundancy Fund | – | 1.2% | Employer-funded |
| Human Resource Development Fund | – | 0.5% | Employer-funded |
| Social Cohesion Fund | – | 2% | Employer-funded; contribution-base rules differ from the Social Insurance cap |
| Central Holiday Fund | – | Where applicable | Rate depends on annual leave entitlement / exemption position |
Do not add the percentages mechanically
The contribution base is not identical for every fund. Social Insurance and specified related funds use maximum insurable earnings, while GHS has its own annual natural-person cap and Social Cohesion follows its own contribution-base rules.
Maximum Insurable Earnings for 2026
From January 2026, the maximum earnings used for calculating contributions to the Social Insurance Fund and specified related funds are €5,742 per month for monthly paid employees and €1,325 per week for weekly paid employees. The ceiling is updated periodically, so payroll should use the figure applicable to the relevant contribution year rather than carrying forward an old limit.
The cap is especially relevant for higher-paid employees, bonuses, commissions and additional remuneration. Payroll should determine which payments constitute insurable earnings and how they interact with the monthly or weekly ceiling.
What Counts as Insurable Earnings?
Social Insurance contributions are calculated on earnings that fall within the statutory definition of insurable earnings. Salary, wages and various additional employment payments can be included. Items such as bonuses, commissions and a thirteenth salary should be reviewed against the contribution period and the applicable maximum earnings ceiling.
The treatment of benefits, expense reimbursements, allowances and other payroll items should not be assumed from their accounting label. The underlying nature of the payment and the employment arrangement determine the correct treatment.
What Does a Cyprus Employer Pay Beyond Social Insurance?
Redundancy Fund – 1.2%
The employer contributes 1.2% to the Redundancy Fund on the applicable earnings base. This is an employer cost and is not deducted from the employee’s net salary.
Human Resource Development Fund – 0.5%
The employer also contributes 0.5% to the Human Resource Development Fund, which supports training and labour-market development programmes.
Social Cohesion Fund – 2%
A 2% employer contribution is payable to the Social Cohesion Fund. The contribution-base rules are different from the Social Insurance maximum-insurable-earnings ceiling, so employers should not automatically cap this contribution at the Social Insurance limit.
Central Holiday Fund
Employers can also have a Central Holiday Fund obligation. The rate depends on the employee’s leave entitlement and the employer’s status. An employer that has obtained the relevant exemption and pays annual leave directly can have a different payroll calculation from an employer participating in the Fund.
GHS Is Separate From Social Insurance
The General Healthcare System is funded separately from Social Insurance. Employees generally contribute 2.65% on remuneration and employers 2.90%. For natural persons, the overall annual income base subject to GHS is capped at €180,000 across the relevant income categories under the GHS rules.
This distinction matters for high earners. Reaching the Social Insurance monthly ceiling does not automatically mean GHS stops at the same point. Payroll should monitor each contribution according to its own statutory base and cap.
Registering an Employer and Employees for Social Insurance
A business that becomes an employer in Cyprus should ensure that the employer registration and employee registrations are completed correctly before payroll runs are treated as routine. Employee details, identification documents, employment terms and start dates need to align across payroll, Social Insurance and tax records.
IBCCS TAX provides Social Insurance services in Cyprus including employee registration and the preparation of Social Insurance declarations.
Social Insurance Payment Deadlines
Employers are generally required to pay contributions by the end of the calendar month following the month for which the contributions are due. If the last day falls on a weekend or public holiday, the due date moves to the next working day under the Social Insurance payment rules.
| Contribution period | General employer payment deadline |
| January | End of February |
| February | End of March |
| March | End of April |
| Any later month | End of the following calendar month |
Late employer contributions can trigger an additional charge that increases with the length of the delay. Payroll and finance teams should therefore reconcile contribution liabilities before the due date rather than treating the payment as a year-end adjustment.
Self-Employed Social Insurance in Cyprus
Self-employed persons fall under a separate Social Insurance contribution framework. From 2024 through 2028, the self-employed person generally bears 16.6% of the applicable insurable income and the state contributes 5.2%, producing a total Social Insurance Fund rate of 21.8%.
The contribution base is commonly determined by occupational category and prescribed insurable income, although the specific position can vary. For 2026, the prescribed insurable income amounts were increased by 3.38%.
| Quarter | Period | Standard payment date |
| Q1 | January – March | 10 May |
| Q2 | April – June | 10 August |
| Q3 | July – September | 10 November |
| Q4 | October – December | 10 February of the following year |
Self-employed professionals should review Social Insurance together with personal income tax, GHS, provisional tax and VAT. See self-employed in Cyprus for the full framework.
Social Insurance and the Cyprus Minimum Wage
Minimum wage is expressed as a gross salary, not a net take-home amount. Social Insurance and GHS employee contributions reduce net pay, while employer contributions sit on top of the gross salary. From 1 January 2026, the national minimum wage is €979 gross per month during the first six months of continuous employment with the same employer and €1,088 after six months, subject to the scope and exclusions of the Minimum Wage Order.
See our Cyprus minimum wage 2026 guide for the detailed rules.
Social Insurance for EU and International Employees
Cross-border employment can require a separate social-security analysis. EU coordination rules can determine which Member State’s social-security system applies, while employees arriving from or working in third countries may need a review of the relevant bilateral arrangements, immigration status and local registration requirements.
Employers should not assume that tax residency and Social Insurance follow the same test. An employee can be tax resident in one country while social-security coverage is determined under a different set of rules.
Common Employer Mistakes
- Applying the Social Insurance cap to contributions that use a different contribution base.
- Using outdated maximum insurable earnings limits.
- Registering an employee late or with inconsistent personal details.
- Treating GHS as part of the Social Insurance percentage rather than as a separate contribution.
- Ignoring employer funds when budgeting the total employment cost.
- Failing to update payroll when an employee receives a bonus, commission or thirteenth salary.
- Missing the end-of-following-month payment deadline.
- Assuming an international employee is automatically subject to Cyprus Social Insurance without checking cross-border coverage rules.
How Social Insurance Fits Into Payroll
A compliant payroll process should calculate gross remuneration, determine PAYE, calculate employee Social Insurance and GHS, calculate employer Social Insurance and employer funds, produce the net salary and then report and pay each liability through the relevant systems. The accounting ledger should reconcile to the payroll reports and statutory declarations.
For the complete workflow, including PAYE and employer reporting, see Payroll in Cyprus.
How IBCCS TAX Can Help
IBCCS TAX supports employers with Social Insurance services in Cyprus, Social Insurance declarations and payroll preparation services. We can coordinate employer registration, employee onboarding, payroll calculations, contribution reporting and ongoing compliance as one process.
Frequently Asked Questions – Social Insurance in Cyprus
1. What is the Social Insurance rate in Cyprus in 2026?
For employees, 8.8% of insurable earnings is paid by the employee and 8.8% by the employer. The state contributes a further 5.2% to the Social Insurance Fund.
2. What is the maximum insurable salary in Cyprus in 2026?
For 2026, the maximum insurable earnings are €5,742 per month for monthly paid employees and €1,325 per week for weekly paid employees for the funds to which the statutory ceiling applies.
3. Does the employer only pay 8.8% Social Insurance?
No. Employers can also pay GHS, Redundancy Fund, Human Resource Development Fund, Social Cohesion Fund and, where applicable, Central Holiday Fund contributions.
4. What is the employee GHS rate?
Employees generally contribute 2.65% on remuneration under the GHS framework. The employer generally contributes 2.90% separately.
5. When are Social Insurance contributions due?
Employer contributions are generally due by the end of the calendar month following the month to which they relate.
6. How much Social Insurance does a self-employed person pay?
A self-employed person generally pays 16.6% of the applicable insurable income under the current contribution schedule, with the state contributing separately.
7. Is Social Insurance the same as PAYE?
No. PAYE is income tax withholding. Social Insurance and GHS are separate statutory contribution systems and must be calculated and reported separately.
Cyprus Non-Dom After 17 Years: Deemed Domicile and the Alternative SDC Method
Cyprus Non-Dom is often described as a 17-year tax benefit,
Read More
Cyprus Non-Dom Eligibility: Domicile of Origin, Domicile of Choice and the 17/20 Rule
Cyprus Non-Dom eligibility is often described too simply. A person
Read More
IBCCS TAX to Attend Plan ₿ Forum 2026 in Lugano, Switzerland
IBCCS TAX will be attending Plan ₿ Forum 2026 in
Read MoreImportant Note: This article provides general information on Cyprus tax and compliance rules. The correct treatment depends on the taxpayer, the nature and source of the income or transaction, tax residency and domicile, available exemptions, applicable double tax treaties and the facts of the case. It should not be treated as a substitute for transaction-specific tax or legal advice.